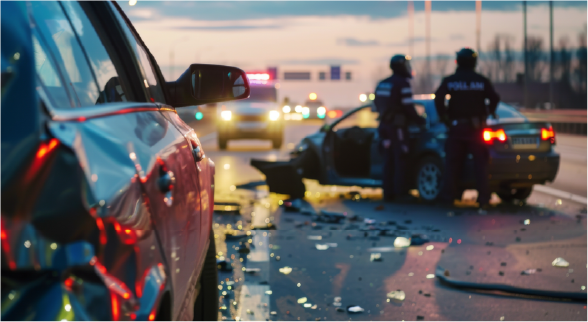
You’ve been injured in a car accident. The other driver caused the crash. You exchange information, talk to the police, and then discover something you weren’t expecting:
The other driver doesn’t have insurance.
It’s an understandably frustrating situation.
If someone else caused your injuries, it seems logical that their insurance company would be responsible for paying your accident-related losses. But what happens when there is no insurance company on the other side?
Fortunately, being hit by an uninsured driver doesn’t necessarily mean you’re out of options.
Missouri requires automobile insurance policies to include uninsured motorist coverage for bodily injury. Depending on the circumstances, that coverage may provide an important source of compensation when the at-fault driver has no insurance.
Understanding how that coverage works, what it may cover, and what to do after the accident can help you protect your rights.
What Is Uninsured Motorist Coverage?
Uninsured motorist coverage, often shortened to UM coverage, is insurance designed to protect you when you’re injured by a driver who doesn’t have liability insurance.
Instead of pursuing compensation through the at-fault driver’s insurer, you may make an uninsured motorist claim through an applicable insurance policy.
That can feel strange.
After all, you’re making a claim involving your own insurance coverage even though you didn’t cause the accident.
But that’s exactly why uninsured motorist coverage exists.
It helps provide protection when the person responsible for your injuries doesn’t have insurance available to compensate you.
Does Missouri Require Uninsured Motorist Coverage?
Missouri law generally requires automobile liability policies issued in the state to include uninsured motorist bodily injury coverage.
That coverage is intended to protect insured individuals who suffer bodily injuries caused by an uninsured motorist.
The amount of coverage available and which policies may apply depend on the specific circumstances of the accident and the insurance policies involved.
Reviewing the actual policy can be important when determining what coverage is available.
What Does Uninsured Motorist Coverage Pay For?
When applicable, uninsured motorist coverage may compensate an injured person for damages the uninsured at-fault driver would otherwise have been responsible for paying.
Depending on the circumstances, that may include:
- Medical expenses
- Future medical care
- Lost wages
- Reduced earning capacity
- Pain and suffering
- Permanent impairment or disability
- Other compensable injury-related losses
The amount available depends on factors such as the severity of your injuries, your damages, the facts surrounding the accident, and the applicable insurance coverage.
What Should You Do After an Accident With an Uninsured Driver?
Finding out the other driver doesn’t have insurance doesn’t change the importance of the basic steps you should take after a collision.
Call the Police
A police report can provide important documentation of the crash, including information about the drivers, vehicles, witnesses, and insurance coverage.
If the other driver says they don’t have insurance or refuses to provide insurance information, don’t try to sort everything out on the side of the road yourself.
Let law enforcement document the situation.
Gather Information
If you’re able to do so safely, collect:
- The other driver’s name and contact information
- Driver’s license information
- Vehicle information
- Photographs of the vehicles
- Photographs of the accident scene
- Witness names and contact information
- Police report information
Seek Medical Attention
Your health should remain the priority.
Some accident injuries aren’t immediately obvious, so seek appropriate medical evaluation if you’re experiencing pain or other symptoms.
Don’t let the other driver’s lack of insurance discourage you from getting necessary medical care.
Notify Your Insurance Company
Your insurer should generally be notified about the accident promptly.
Be accurate about what happened, but remember that an uninsured motorist claim may eventually involve your own insurance company evaluating your injuries and damages.
That brings us to an important point.
Is Your Own Insurance Company Automatically on Your Side?
You pay your premiums. You’ve been injured by someone else. You’re now making a claim under coverage you purchased.
It would be reasonable to assume the process should be simple.
Unfortunately, insurance claims don’t always work that way.
Even when you’re making an uninsured motorist claim under an applicable policy, the insurance company may still investigate:
- Who caused the accident
- Whether the other driver was actually uninsured
- Whether your injuries resulted from the collision
- The extent of your medical treatment
- Whether your treatment was reasonable and necessary
- The value of your damages
The insurer may also request medical records, statements, or other information while evaluating the claim.
That’s why it’s important to treat an uninsured motorist claim seriously, even when you’re dealing with an insurance company you consider “your own.”
Related: How to Deal With Insurance Adjusters After a Missouri Car Accident.
What If the Driver Has Insurance, But Not Enough?
This is a slightly different situation.
An uninsured driver has no applicable liability insurance.
An underinsured driver has insurance, but the available liability coverage may not be enough to compensate you fully for serious injuries.
For example, imagine your medical expenses and other damages are substantial, but the at-fault driver’s insurance coverage is insufficient to address the full value of your claim.
Whether additional coverage is available through your own policy depends on the coverage you’ve purchased and the terms of the applicable insurance policies.
This is why reviewing the policy itself matters rather than assuming all uninsured and underinsured motorist claims work the same way.
What Happens in a Hit-and-Run Accident?
Uninsured motorist issues can also arise when the driver who caused the accident leaves the scene and cannot be identified.
If you’ve been injured in a hit-and-run accident:
- Call law enforcement immediately.
- Provide as much information about the vehicle and driver as possible.
- Look for witnesses.
- Photograph the scene.
- Ask nearby businesses or property owners whether surveillance cameras may have captured the collision.
- Notify your insurance company.
- Seek medical treatment for your injuries.
The specific requirements for uninsured motorist coverage in a hit-and-run situation can depend on Missouri law and the applicable insurance policy, so these cases deserve careful review.
What If You Were a Passenger?
You don’t necessarily have to be driving your own vehicle for uninsured motorist coverage to become relevant.
If you’re injured as a passenger by an uninsured driver, there may be coverage available through one or more applicable policies.
Determining which insurance applies can become complicated, particularly when multiple vehicles, household policies, or insurance carriers are involved.
An attorney can review the policies and circumstances to identify potential sources of coverage.
What If You Were Hit While Walking or Riding a Bicycle?
Uninsured motorist coverage isn’t necessarily limited to someone sitting behind the wheel of a car.
Depending on the circumstances and applicable insurance policy, coverage may also become relevant when an insured person is struck by an uninsured motorist while:
- Walking
- Riding a bicycle
- Riding as a passenger
- Occupying another vehicle
Again, the details of the policy and accident matter.
Why Medical Documentation Still Matters
The fact that the other driver was uninsured doesn’t eliminate the need to establish your injuries and damages.
Your medical records may help document:
- When symptoms began
- Your diagnosis
- Treatment you’ve received
- Whether surgery or rehabilitation is necessary
- Time you’ve missed from work
- Permanent limitations
- Future medical needs
If symptoms develop after the accident rather than immediately at the scene, don’t ignore them.
Related: Delayed Pain After a Missouri Car Accident: Can You Still Have an Injury Claim?
Should You Give the Insurance Company a Recorded Statement?
An insurance adjuster may ask you to provide a recorded statement about the accident.
Before agreeing, understand why the statement is being requested and what your policy requires.
Seemingly harmless comments about how the accident occurred, how you’re feeling, or previous injuries can become relevant later when the insurer evaluates the claim.
You should be truthful when communicating with an insurance company, but you don’t need to guess or speculate about information you don’t know.
If you’re unsure about your obligations or concerned about the questions you’re being asked, consider speaking with an attorney first.
What If the Insurance Company Disputes Your UM Claim?
An uninsured motorist claim can still result in disagreements over liability, coverage, medical treatment, or the value of your injuries.
Potential disputes may involve questions such as:
- Who caused the accident?
- Was the other driver actually uninsured?
- Does the policy cover the accident?
- Are your injuries related to the collision?
- How serious are your injuries?
- What compensation is appropriate?
When those disputes arise, having an attorney who understands both personal injury law and insurance coverage issues can become particularly important.
When Should You Talk to a Missouri Car Accident Attorney?
You may want to seek legal guidance if:
- The at-fault driver has no insurance.
- You were injured in a hit-and-run.
- The other driver’s insurance isn’t enough to cover significant injuries.
- You’re unsure which insurance policies may apply.
- Your insurance company disputes coverage.
- You’re being asked to provide a recorded statement.
- Your injuries require significant or ongoing medical treatment.
- You’ve received a settlement offer and aren’t sure whether it fairly reflects your losses.
The earlier applicable insurance coverage is identified, the easier it may be to understand your options.
Frequently Asked Questions
Can I still recover compensation if the driver who hit me has no insurance?
Potentially. Uninsured motorist coverage may provide compensation when an uninsured driver causes bodily injuries. The coverage available depends on the facts of the accident and the applicable insurance policy.
Do I have uninsured motorist coverage in Missouri?
Missouri generally requires automobile liability insurance policies issued in the state to include uninsured motorist bodily injury coverage. The amount and application of coverage should be confirmed by reviewing the applicable policy.
Will my own insurance company pay my claim?
If uninsured motorist coverage applies, you may pursue compensation under the applicable policy. However, the insurer will still investigate the accident, your injuries, and the value of the claim.
What if the other driver leaves the scene?
Report a hit-and-run accident to law enforcement immediately and notify your insurance carrier. Uninsured motorist coverage may become relevant depending on the circumstances and applicable policy.
Is an uninsured motorist claim the same as an underinsured motorist claim?
No. Uninsured motorist coverage involves a driver who lacks applicable insurance. Underinsured motorist issues arise when the at-fault driver has insurance, but the available coverage isn’t sufficient to fully compensate the injured person. Whether underinsured motorist coverage is available depends on the policy.
The Hines & Wilson Law Firm Is Here to Help
Discovering that the driver who caused your accident doesn’t have insurance can make an already stressful situation feel even more uncertain.
But a lack of insurance on the other driver’s part doesn’t necessarily mean you have nowhere to turn.
The Hines & Wilson Law Firm helps people injured in Missouri car accidents identify available insurance coverage, understand their rights, and pursue compensation for their injuries and losses.
If you’ve been injured by an uninsured driver, involved in a hit-and-run accident, or have questions about the insurance coverage available after a crash, contact The Hines & Wilson Law Firm to discuss your options.
Scott Wilson
Partner | Workers’ Compensation & Personal Injury Attorney
Scott Wilson has been fighting for injured workers, accident victims, and families whose lives have been altered by serious injuries for over 25 years. Throughout his career, he has exclusively represented individuals harmed by workplace accidents and the negligence of others, earning a reputation as one of Missouri’s leading advocates in workers’ compensation and personal injury law.
As a partner of The Hines & Wilson Law Firm, Scott has dedicated his practice to helping injured individuals navigate complex legal and insurance systems while pursuing the compensation, medical treatment, and benefits they need to move forward. His experience spans workplace injury claims, catastrophic injury cases, motor vehicle accidents, and wrongful death matters, giving him a comprehensive understanding of the challenges clients face after a life-changing injury.
Scott’s commitment to excellence in workers’ compensation law has earned him one of the profession’s most prestigious distinctions: induction as a Fellow of the College of Workers’ Compensation Lawyers. Fellowship is reserved for attorneys who have demonstrated exceptional professional achievement, integrity, leadership, and expertise in the practice of workers’ compensation law. The honor recognizes lawyers who have earned the respect of their peers, judges, and the legal community through their advocacy and dedication to the profession. Scott is among a select group of Missouri attorneys to receive this distinction. There have been only 25 lawyers decorated as Fellows of the College from Missouri, ever.
Scott is also a member of the Workers’ Injury Law & Advocacy Group (WILG), a national nonprofit organization dedicated to protecting the rights of injured workers and their families. Through WILG, he collaborates with attorneys and advocates from across the country to stay informed on emerging issues in workers’ compensation law and to advance the interests of individuals affected by workplace injuries and occupational illnesses.
In addition to his work on behalf of injured clients, Scott is widely respected within the legal profession. He has served on the Board of Governors of the Missouri Association of Trial Attorneys for 20 years, helping advance the interests of injury victims throughout the state, and protecting their right to justice. He is also an active member of the American Association for Justice (AAJ), the Boone County Bar Association, The Bar Association of Columbia, and The Missouri Bar.
Scott’s legal knowledge and advocacy have earned repeated recognition from national legal organizations. He has been selected to The National Trial Lawyers Top 100, an invitation-only distinction recognizing attorneys who demonstrate superior qualifications, trial results, leadership, and professional excellence. He has received this honor repeatedly throughout his career, reflecting a longstanding commitment to achieving results for injured clients.
Beyond the courtroom, Scott is dedicated to serving his community and supporting families affected by workplace tragedies. He served on the Board of KIDS’ CHANCE of Missouri, a nonprofit organization that provides scholarships to children of workers who have been seriously injured, permanently disabled, or killed on the job. His involvement reflects the same commitment that has defined his legal career: standing beside hardworking families when they need support the most.
Scott has also shares his knowledge with fellow attorneys and Judges as he is often invited to present at professional education programs and speaking engagements as an expert on personal injury and workers’ compensation cases. His contributions to legal education further reflect his standing as a trusted resource within Missouri’s legal community.
A graduate of the University of Missouri, Scott earned his Bachelor of Arts degree in 1995 and his Juris Doctor degree in 1998. Since then, he has remained committed to one mission: helping injured people obtain the justice, benefits, and financial recovery they deserve.
When he is not advocating for clients or serving the legal community, Scott enjoys spending time with his family, attending Mizzou games, and serving on the Board of community organizations, but is most proud to be Girl Dad to two daughters.
Areas of Concentrated Experience:
- Missouri Workers’ Compensation Claims
- Permanent Total Disability Claims
- Workplace Accident Injuries
- Construction Accidents
- Repetitive Trauma Injuries
- Motor Vehicle Accidents
- Truck Accidents
- Wrongful Death Claims
- Serious and Catastrophic Injuries
Professional Associations & Leadership
- Fellow, College of Workers’ Compensation Lawyers
- Board of Governors, Missouri Association of Trial Attorneys
- Member, Workers’ Injury Law & Advocacy Group (WILG)
- Member, American Association for Justice (AAJ)
- Member, Missouri Bar
- Member, Boone County Bar Association